Saving money can feel difficult when everyday expenses keep increasing. Rent, groceries, transportation, subscriptions, bills, and unexpected expenses can quickly consume your monthly income.
The good news is that you don’t necessarily need to earn more money to start saving. Small changes to your spending habits can make a meaningful difference over time.
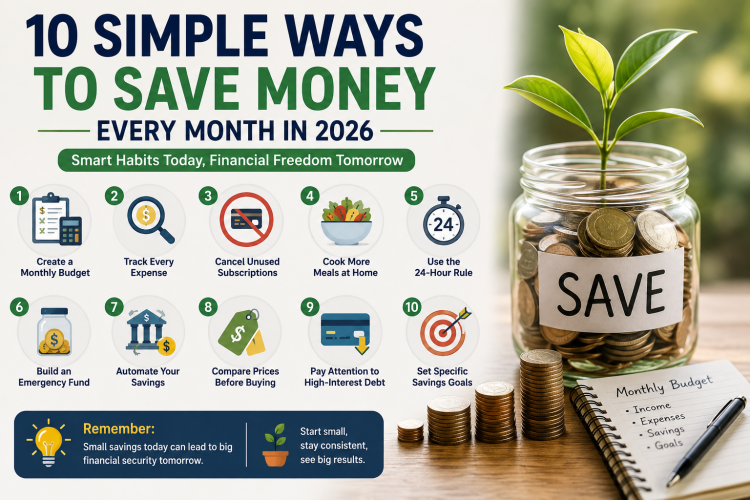
Here are 10 simple ways to save money every month in 2026 without making your life unnecessarily difficult.
1. Create a Monthly Budget
The first step toward saving money is knowing where your money goes.
Write down your monthly income and divide your expenses into categories such as:
- Housing
- Food
- Transportation
- Utilities
- Entertainment
- Shopping
- Debt payments
- Savings
A budget doesn’t have to be complicated. Even a simple spreadsheet or budgeting app can help you identify where you’re spending too much.
2. Track Every Expense
Small purchases can add up quickly.
A $5 coffee, $10 delivery fee, or $15 subscription may not seem significant individually, but repeated purchases can become hundreds of dollars over a year.
For one month, record every purchase you make.
At the end of the month, review your spending and look for expenses you can reduce or eliminate.
3. Cancel Unused Subscriptions
Streaming services, fitness memberships, software subscriptions, cloud storage, and other recurring payments can quietly drain your bank account.
Check your bank or credit-card statements for recurring charges.
Ask yourself:
“Did I use this service during the last 30 days?”
If the answer is no, consider canceling it.
Even eliminating three $10 monthly subscriptions saves $360 per year.
4. Cook More Meals at Home
Eating out and ordering delivery can become one of the largest flexible expenses in a household.
You don’t need to stop eating at restaurants completely.
Instead, try preparing more meals at home.
Plan your meals before shopping and make a grocery list. Buying only what you need can also reduce food waste.
Cooking a few additional meals at home each week can potentially save a significant amount over the course of a year.
5. Use the 24-Hour Rule
Impulse purchases are a common reason people spend more than planned.
Before buying something you don’t actually need, wait 24 hours.
For more expensive purchases, consider waiting a week.
After the waiting period, ask yourself:
- Do I still need it?
- Will I use it regularly?
- Does it fit my budget?
- Would I rather save this money?
You may discover that many purchases were simply impulse decisions.
6. Build an Emergency Fund
An emergency fund is money set aside for unexpected expenses.
For example, you might suddenly need to pay for:
- A medical bill
- Car repairs
- Home repairs
- Emergency travel
- A temporary loss of income
Start with a small target if necessary.
Saving your first $500 or $1,000 can provide a useful financial cushion. Over time, you can work toward building a larger emergency fund based on your personal circumstances.
Keep emergency savings somewhere accessible and separate from everyday spending money.
7. Automate Your Savings
One of the easiest ways to save consistently is to automate the process.
Set up an automatic transfer from your checking account to your savings account shortly after receiving your income.
For example, saving $50 per week would add up to:
$50 × 52 weeks = $2,600 per year
The exact amount matters less than developing a consistent habit.
8. Compare Prices Before Major Purchases
Before buying expensive items, compare prices from several sellers.
This is particularly important for:
- Electronics
- Appliances
- Insurance
- Travel
- Internet services
- Furniture
Don’t automatically choose the cheapest option, however. Consider quality, warranty, customer service, and long-term value as well.
A slightly more expensive product that lasts longer may ultimately cost less.
9. Pay Attention to High-Interest Debt
Interest can make debt significantly more expensive.
Credit-card balances and other high-interest debt can grow quickly when only minimum payments are made.
If you have multiple debts, review their interest rates and balances. Paying down expensive debt can be an important part of improving your overall financial position.
If you’re struggling with debt, consider speaking with a qualified financial professional or a reputable nonprofit credit counselor before making major financial decisions.
10. Set Specific Savings Goals
Saving money is easier when you have a clear reason for doing it.
Instead of saying:
“I want to save more money.”
Set a specific goal such as:
“I want to save $3,000 for an emergency fund within 12 months.”
Then divide the target into smaller monthly or weekly amounts.
For example, saving $3,000 over 12 months means approximately $250 per month.
A specific target makes your progress easier to measure and can keep you motivated.
How Much Money Should You Save Each Month?
There is no single amount that works for everyone.
Your ideal savings amount depends on your income, expenses, debt, family situation, financial goals, and location.
Instead of comparing your savings with someone else’s, focus on improving your own financial habits.
If you currently save nothing, starting with even a small amount is progress.
As your income increases or expenses decrease, you can gradually increase your savings rate.
Final Thoughts
Saving money doesn’t require completely eliminating everything you enjoy.
The most effective approach is usually to identify unnecessary expenses, create a realistic budget, automate savings, and make intentional spending decisions.
Start with one or two changes this month. Once those habits become routine, add another.
Over time, small financial decisions can add up to substantial savings and give you greater control over your money.
The goal isn’t simply to spend less. It’s to make sure more of your money goes toward the things that matter most to you.
Disclaimer: This article is for general educational purposes and is not personalized financial advice. Consider your individual circumstances and consult a qualified financial professional before making significant financial decisions.


No Comments
Leave Comment